The consumer credit market is filled with technical acronyms that can feel overwhelming: Nominal Rate (TAN), APR (TAEG), Total Cost (MTIC)... If you have never applied for financing or want to understand what is truly inside a bank offer, this beginner guide clarifies every concept simply and transparently.
1. Nominal Interest Rate: The Window Price (Yet Incomplete)
The nominal annual rate is the pure interest charged by the lender on borrowed funds across one year.
2. APR (TAEG): The True Comparative Compass
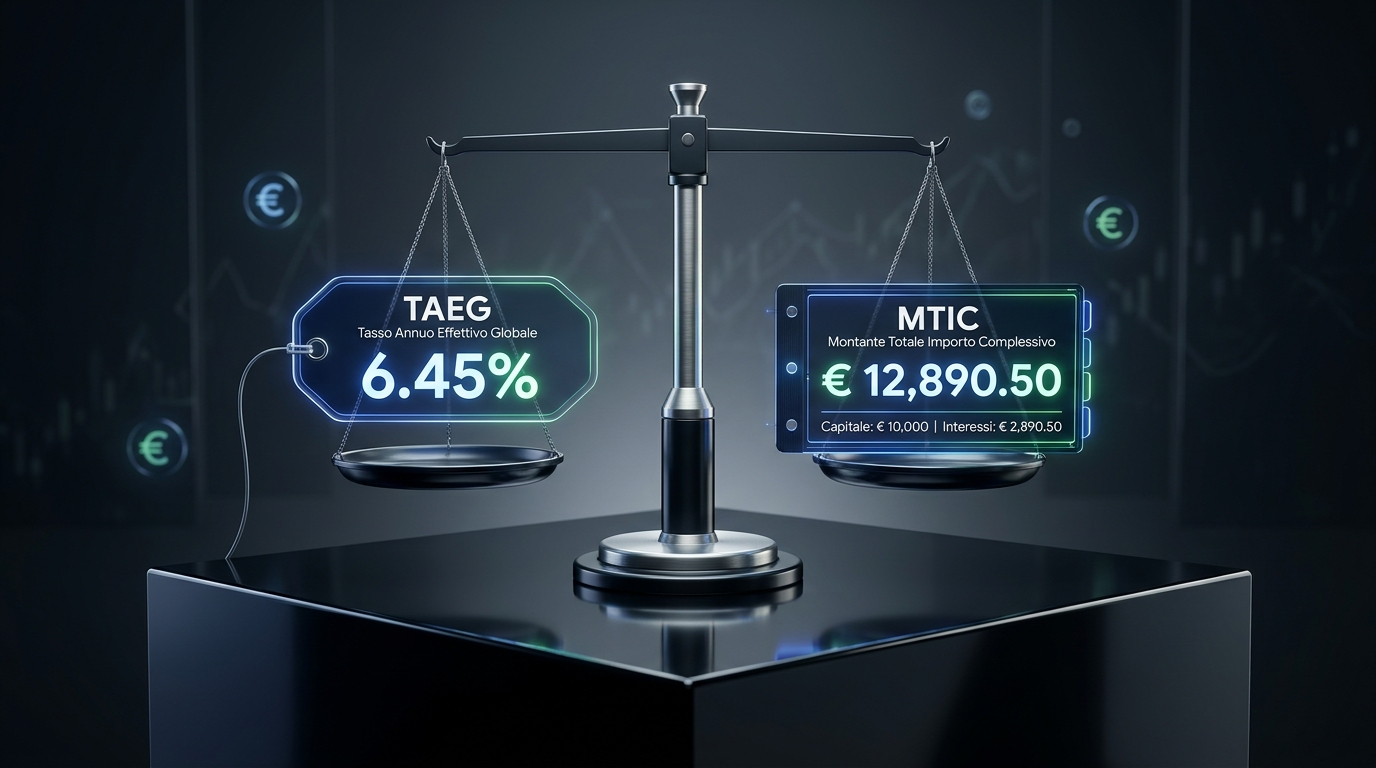
The Annual Percentage Rate (APR / TAEG) is the mandatory European regulatory standard. It combines all compulsory costs needed to obtain financing:
- Base borrowing interest;
- Statutory taxes and stamp duties;
- Application fees and opening commissions;
- Mandatory insurance required by the lender;
- Account maintenance fees tied to credit servicing.
Golden Rule for Smart Borrowers
Never compare lenders based on the nominal interest rate alone. Always compare using the APR (TAEG). An offer with a slightly higher nominal rate can be significantly cheaper if it waives application fees and commissions!
3. Total Amount Repayable (MTIC): The Real Euro Figure
To evaluate financing without getting lost in percentages, look at the total amount repayable by the borrower (referred to as MTIC in countries like Portugal). It states the exact amount leaving your pocket across the life of the loan:
| Metric | Offer A (Zero Hidden Fees) | Offer B (Hidden Commission) |
|---|---|---|
| Requested Amount | €5,000 (36 months) | €5,000 (36 months) |
| Nominal Rate Advertised | 7.20% | 6.50% (teaser discount) |
| Setup & Insurance Fees | €0 | €220 fees + compulsory insurance |
| True APR (TAEG) | 7.90% | 10.40% |
| Total Amount Repaid | €5,614.80 | €5,820.40 (+ €205.60) |
4. Regulatory Caps & Usury Limits
Across European member states (such as Banco de Portugal or Bank of France), central banking authorities publish strict quarterly maximum usury caps. No licensed entity may legally charge an APR above these statutory thresholds.